

Our 101 guide to help you decide what makes an ideal choice for you – selling your gold or taking a loan against it. Read on.
If you have gold jewellery, coins or bullion and need some extra money, you may be deciding between selling your gold or taking a loan against it. Both options can give you access to cash, but they work differently. Selling means giving up your gold in exchange for payment, while a gold loan allows you to borrow against its value and keep ownership of the gold.
Our all-inclusive guide will walk you through both options so you can decide which makes more sense for you. Let’s dive in!
How selling gold works
Selling gold is one of the simplest ways to turn your gold into cash. You take your gold jewellery, coins, bullion, or even scrap to a licensed buyer in Brisbane. They check the purity, weigh it, and compare it with the current market price of gold. If you are happy with the offer, you will receive payment instantly via cash or bank transfer.
In simple terms, selling gold means exchanging your gold for money based on its current value. The price is usually worked out using three main factors:
- The live market price of gold
- The purity of your gold (such as 9k, 14k, 18k, or 22k)
- The total weight of your gold
Selling gold can be a good option when the jewellery is broken, unused, or no longer needed. It also works well if you are comfortable letting go of the item permanently and prefer a one-time payment without any future commitments.
How buyers calculate your gold’s value
A trusted gold buyer in Brisbane will assess your gold to ascertain its worth based on three major factors:
- the weight of your gold item,
- purity of your gold item, and
- the live market rate of gold at that time
In Australia and many other markets, gold is commonly priced by the troy ounce, while in countries such as India, gold is often measured and sold by the gram.
Gold purity tells you how much actual gold an item contains. Most jewellery isn’t made from pure gold. Other metals are added to make it stronger and more suitable for everyday wear, as pure gold is naturally soft. Refer to the table below for gold purity in karats and gold percentage.
The market price is the current global price of gold. It changes throughout the day and can be checked online at any time.
Hence,
Gold Value = Weight (grams) × Purity (%) × Current Gold Price (per gram)
Let’s assume:
- Weight of your gold = 10 grams
- Purity = 75% (18K gold)
- Gold Price (live market rate) = A$ 100 per gram
Your gold’s value = 10 × 0.75 × 100 = A$ 750
*Please note that most gold buyers will offer a percentage of this value (called payout rate), not the full 100%, because they factor in refining and business costs.
How a gold loan works
A gold loan is when you use your gold as security to borrow money from a lender. You repay the loan with interest, and once it’s fully paid, you get your gold back. Instead of selling your gold, you hand it over temporarily to a lender, i.e., a bank, a finance company, or a trusted gold dealer like Cash Your Gold.
*Security means that the gold acts as a guarantee to the lender that if you can’t repay the loan, they can keep or sell your gold to recover the money they lent you.
Once you’ve repaid the full loan amount, including interest and any applicable fees, within the agreed timeframe, the lender returns your gold to you.
Interest rates and fees can vary between lenders, so it’s important to check the total cost of the loan before agreeing to it. A pawnbroker may also offer a loan against your gold, but the terms, interest rate, fees and conditions can differ. Make sure you understand the full cost and what happens if you can’t repay the loan on time.
Selling gold vs. gold loan: A comparison
Here’s a simple comparison to make the key differences easy to see at a glance.
| Factor | Selling gold | Gold loan |
| Do you keep ownership? | No, the gold is sold permanently | Yes — you get it back after repayment |
| Do you need to repay anything? | No, nothing to pay back | Yes — the loan plus interest must be repaid |
| How much cash do you receive? | Full assessed value of your gold | A percentage of the gold’s value (usually 60–75%) |
| Is there an ongoing cost? | No ongoing costs at all | Yes — interest accumulates while the loan is open |
| How quickly can you get money? | Immediately on the same visit | Usually, the same day or the next day |
| What’s the long-term impact? | Gold is gone permanently | Gold is returned if the loan is repaid on time |
| Risk involved? | Low, as it has no repayment obligations | Higher, as interest rates and fees can increase the overall cost of the loan. If you don’t repay the loan within the agreed timeframe, you may also risk losing your gold. |
Do I keep ownership of my gold with a gold loan?
This is one of the biggest reasons people consider a gold loan instead of selling. With a gold loan, you use your gold as security to borrow, rather than selling it permanently. With Cash Your Gold’s Gold Loan offering, your precious metal, like gold, is kept securely while the loan is active and returned once the loan is repaid.
However, you should always understand the loan agreement, repayment requirements and what happens if you do not repay before taking the loan.
The advantages of selling gold
Here are the main reasons why selling gold is the simpler and more preferable solution:
- No repayment stress: Once you sell your gold, there’s no loan to worry about, no monthly repayments to keep track of, and no interest piling up.
- No interest costs: With a loan, you always pay back more than you borrowed because of the interest. When you sell your precious metal, you receive the full assessed value and keep every cent.
- You receive the full value of your gold: A gold loan only gives you a portion of your gold’s value (somewhere between 60 and 75 per cent). When you sell, you receive the full value based on weight, purity and the current market rate.
- No risk of losing the gold to debt: Once you’ve sold your precious metal and received your money, the transaction is complete. You won’t lose your gold if you can’t repay the loan with interest.
The benefits of a gold loan
Here’s when taking a gold loan can be the smarter choice.
- You keep ownership of your gold: If your gold has sentimental value, then a loan lets you access cash without parting with it permanently. Once you repay what you owe, you get it back.
- It’s useful for short-term needs: If you need money for a few months to cover an unexpected bill, a gap between jobs, or a short-term business expense, a gold loan is a better option, as you can take instant cash without losing your asset.
- You can benefit if gold prices rise: If gold prices go up significantly after you sell, you’ve missed out on that. With a loan, your gold is always yours, so if prices rise by the time you repay, the gold you get back is worth more.
- It doesn’t require a credit check in most cases: Gold-backed loans don’t require a credit check, as the gold itself serves as collateral and is valued solely by the value of your items; therefore, they are generally faster and more accessible than a personal loan.
Cash Your Gold’s actual interest rates as of 2026
Cash Your Gold offers gold loan services with no hidden fees or surprises, and rates are available for 4 loan durations: 7 days, 14 days, 30 days, and 90 days. Our gold loan rates decrease as the loan amount increases, meaning larger loans attract lower interest rates. Here’s a table for your quick view.
| Loan Amount | 7 Days | 14 Days | 30 Days | 90 Days |
| A$200+ | 5% | 6% | 10% | 10% |
| A$1,000+ | 4% | 5% | 8% | 8% |
| A$4,000+ | 3.50% | 4% | 7% | 7% |
| A$7,000+ | 3% | 4% | 6% | 6% |
| A$10,000+ | 2.50% | 3% | 5% | 5% |
| A$20,000+ | 1.50% | 2.50% | 4% | 4% |
| A$30,000+ | 1.50% | 2% | 3% | 3% |
Please note that loan eligibility, valuation, and final loan amount are subject to the live market price of gold at the time of assessment.
What should you ask before selling or taking a gold loan?
Whether you are speaking to a gold buyer or a lender, you must get clarity on the following questions while selling your gold or taking a gold loan.
Before selling, ask:
- How was my gold valued?
- What is its tested purity?
- What is its weight?
- What gold market rate is being used?
- What is the final amount I will receive?
- Are there any fees or charges?
- Am I under any obligation to accept the offer?
Before taking a gold loan, ask:
- How much can I borrow?
- What interest rate applies to my loan amount?
- How long is the loan term?
- How much will I need to repay in total?
- Can I repay early?
- Can I extend the loan if I need more time?
- What happens if I cannot repay on time?
- What happens to my gold if the loan is not repaid?
Getting clear answers to these questions can make your decision much easier.
Gold Loan vs Selling Gold: Which one is better for you?
If you need some extra money and have gold with you, you may be wondering whether you should sell it or take a loan against it. Both options can help you get the money you need, but the main difference is what happens to your gold.
- When you sell your gold, you give it away and get paid for its value. Once the sale is done, you don’t have to repay anything, but you also don’t get the gold back.
- With a gold loan, you don’t sell your gold. You use it as security to borrow money, and once you repay the loan and the applicable interest, you can get your gold back, as per the agreed terms.
So, which one should you choose? If you have gold that you no longer need and are happy to let go of, selling it may be the simpler option. But if you only need money for a short time and want to keep your gold, a gold loan may make more sense.
The right choice really comes down to your situation, how much money you need, whether you can repay the loan on time, and whether you want to keep your gold.
At Cash Your Gold, customers are guided through both options with honest advice and clarity, so you can decide confidently and move forward on your own terms.
Talk to our experts:
Get in touch
Or Visit
Our Brisbane stores
North Brisbane
Chermside
Located opposite Westfield Chermside, serving Chermside and surrounding North Brisbane suburbs.
-
Address
Suite 5, 832 Gympie Rd, Chermside QLD 4032, Australia -
Phone
(07) 49 390 234 -
Email
[email protected] -
Hours
Monday to Friday: 9 am to 5 pm | Saturday: 10 am to 4 pm | Sunday: Closed
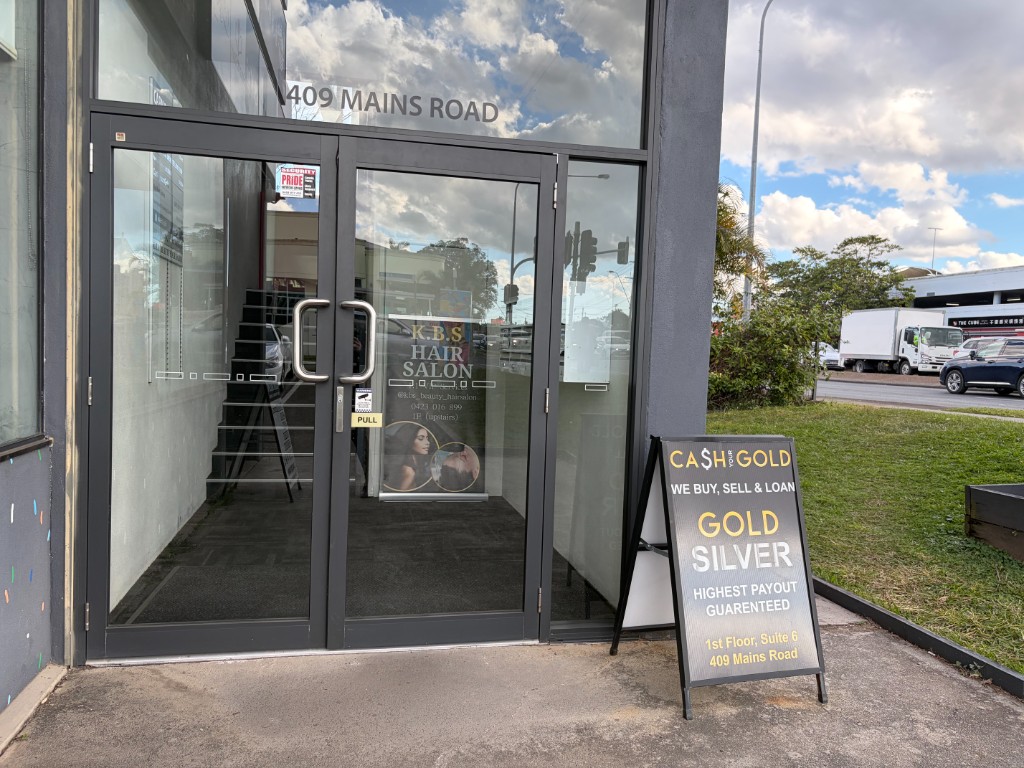
South Brisbane
Sunnybank
Located on Mains Road in Macgregor, serving Sunnybank and surrounding South Brisbane suburbs.
-
Address
Level 1, Suite 6/409 Mains Rd, Macgregor QLD 4109, Australia -
Phone
(07) 2142 6862 -
Email
[email protected] -
Hours
Monday to Friday: 9 am to 5 pm | Saturday: 10 am to 4 pm | Sunday: Closed
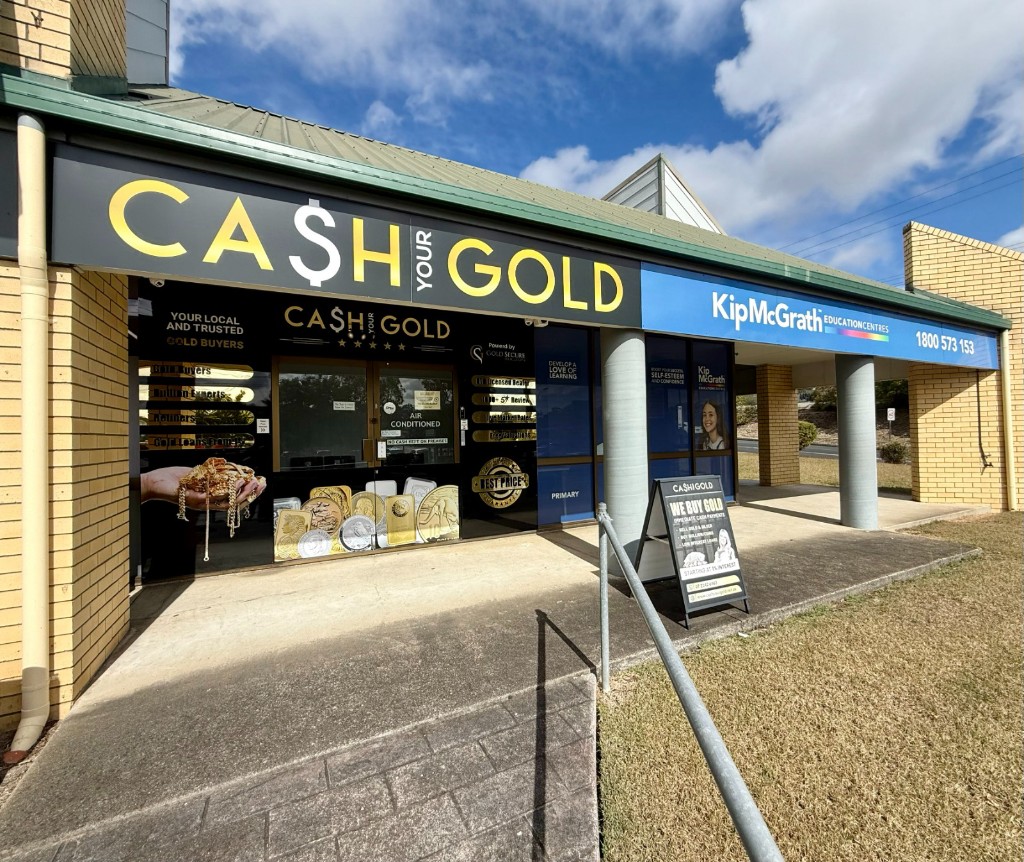
Logan
Browns Plains
Located in Regents Park near Browns Plains, serving Browns Plains and surrounding Logan suburbs.
-
Address
Unit 3/3376 Mount Lindesay Hwy, Regents Park QLD 4118, Australia -
Phone
(07) 2142 6482 -
Email
[email protected] -
Hours
Monday to Friday: 9 am to 5 pm | Saturday: 10 am to 4 pm | Sunday: Closed
Frequently Asked Questions (FAQs)
Q: Is it better to sell gold or take a gold loan?
A: It depends on your situation. Selling gives you money without creating a repayment obligation, but you permanently give up the gold. A gold loan lets you borrow against your gold and potentially get it back after repayment, but you’ll need to repay the loan plus applicable interest within the agreed timeframe.
Q: What is the difference between a gold loan and selling gold?
A: When you sell gold, you exchange it for money, and the transaction is generally final. With a gold loan, your gold is held as security for the loan and can be returned after you repay the loan and applicable interest according to the agreed terms.
Q: Do I keep ownership of my gold with a gold loan?
A: Yes. With a gold loan, you don’t permanently sell your gold. Cash Your Gold keeps your precious metal securely while the loan is active. Once you’ve repaid the loan and applicable interest, your gold is returned to you according to the agreed terms.
Q: How much can I borrow against my gold?
A: The amount you can borrow through Cash Your Gold depends on factors such as your gold’s weight, purity and current market value, as well as Cash Your Gold’s lending criteria. The amount can therefore vary from one item to another.
Q: What interest rate applies to a gold loan?
A: The interest rate and any applicable fees can affect the total amount you repay. Cash Your Gold will provide the relevant loan terms, including the applicable interest, before you agree to the loan. Make sure you understand the total repayment amount and payment timeframe before proceeding.
Q: Can I extend my gold loan payment time?
A: Yes. Cash Your Gold customers can extend their loan by 30 days by paying the applicable interest for the previous period. Check the terms of your loan to understand the applicable interest and extension conditions.
Q: When is selling gold a better option than taking a gold loan?
A: Selling may be more suitable if you no longer want the gold, don’t want a repayment obligation or are comfortable permanently giving up the item. You won’t have a loan or interest to repay after the sale.
Q: When is a gold loan a better option than selling gold?
A: A gold loan may be more suitable if your need for money is temporary, you want to keep your gold and you have a realistic plan to repay the loan, including the applicable interest, within the agreed timeframe.
Q: What happens if I cannot repay my gold loan?
A: Your gold is held as security for the loan, so failing to repay within the agreed timeframe can put your gold at risk. The exact consequences depend on the loan terms. Before taking a loan, make sure you understand the interest, repayment timeframe, extension options and what happens if you don’t repay.
